


1099-NEC vs 1099-MISC: Which form to use
Amounts last verified on August 30th 2026
Michel Myara is co-founder and product designer at looch, where he designs the ecosystem small businesses use to get paid and manage spend while keeping penny-perfect books.
Services belong on the 1099-NEC, while other reportable payments belong on the 1099-MISC: The thresholds aren’t all $2,000
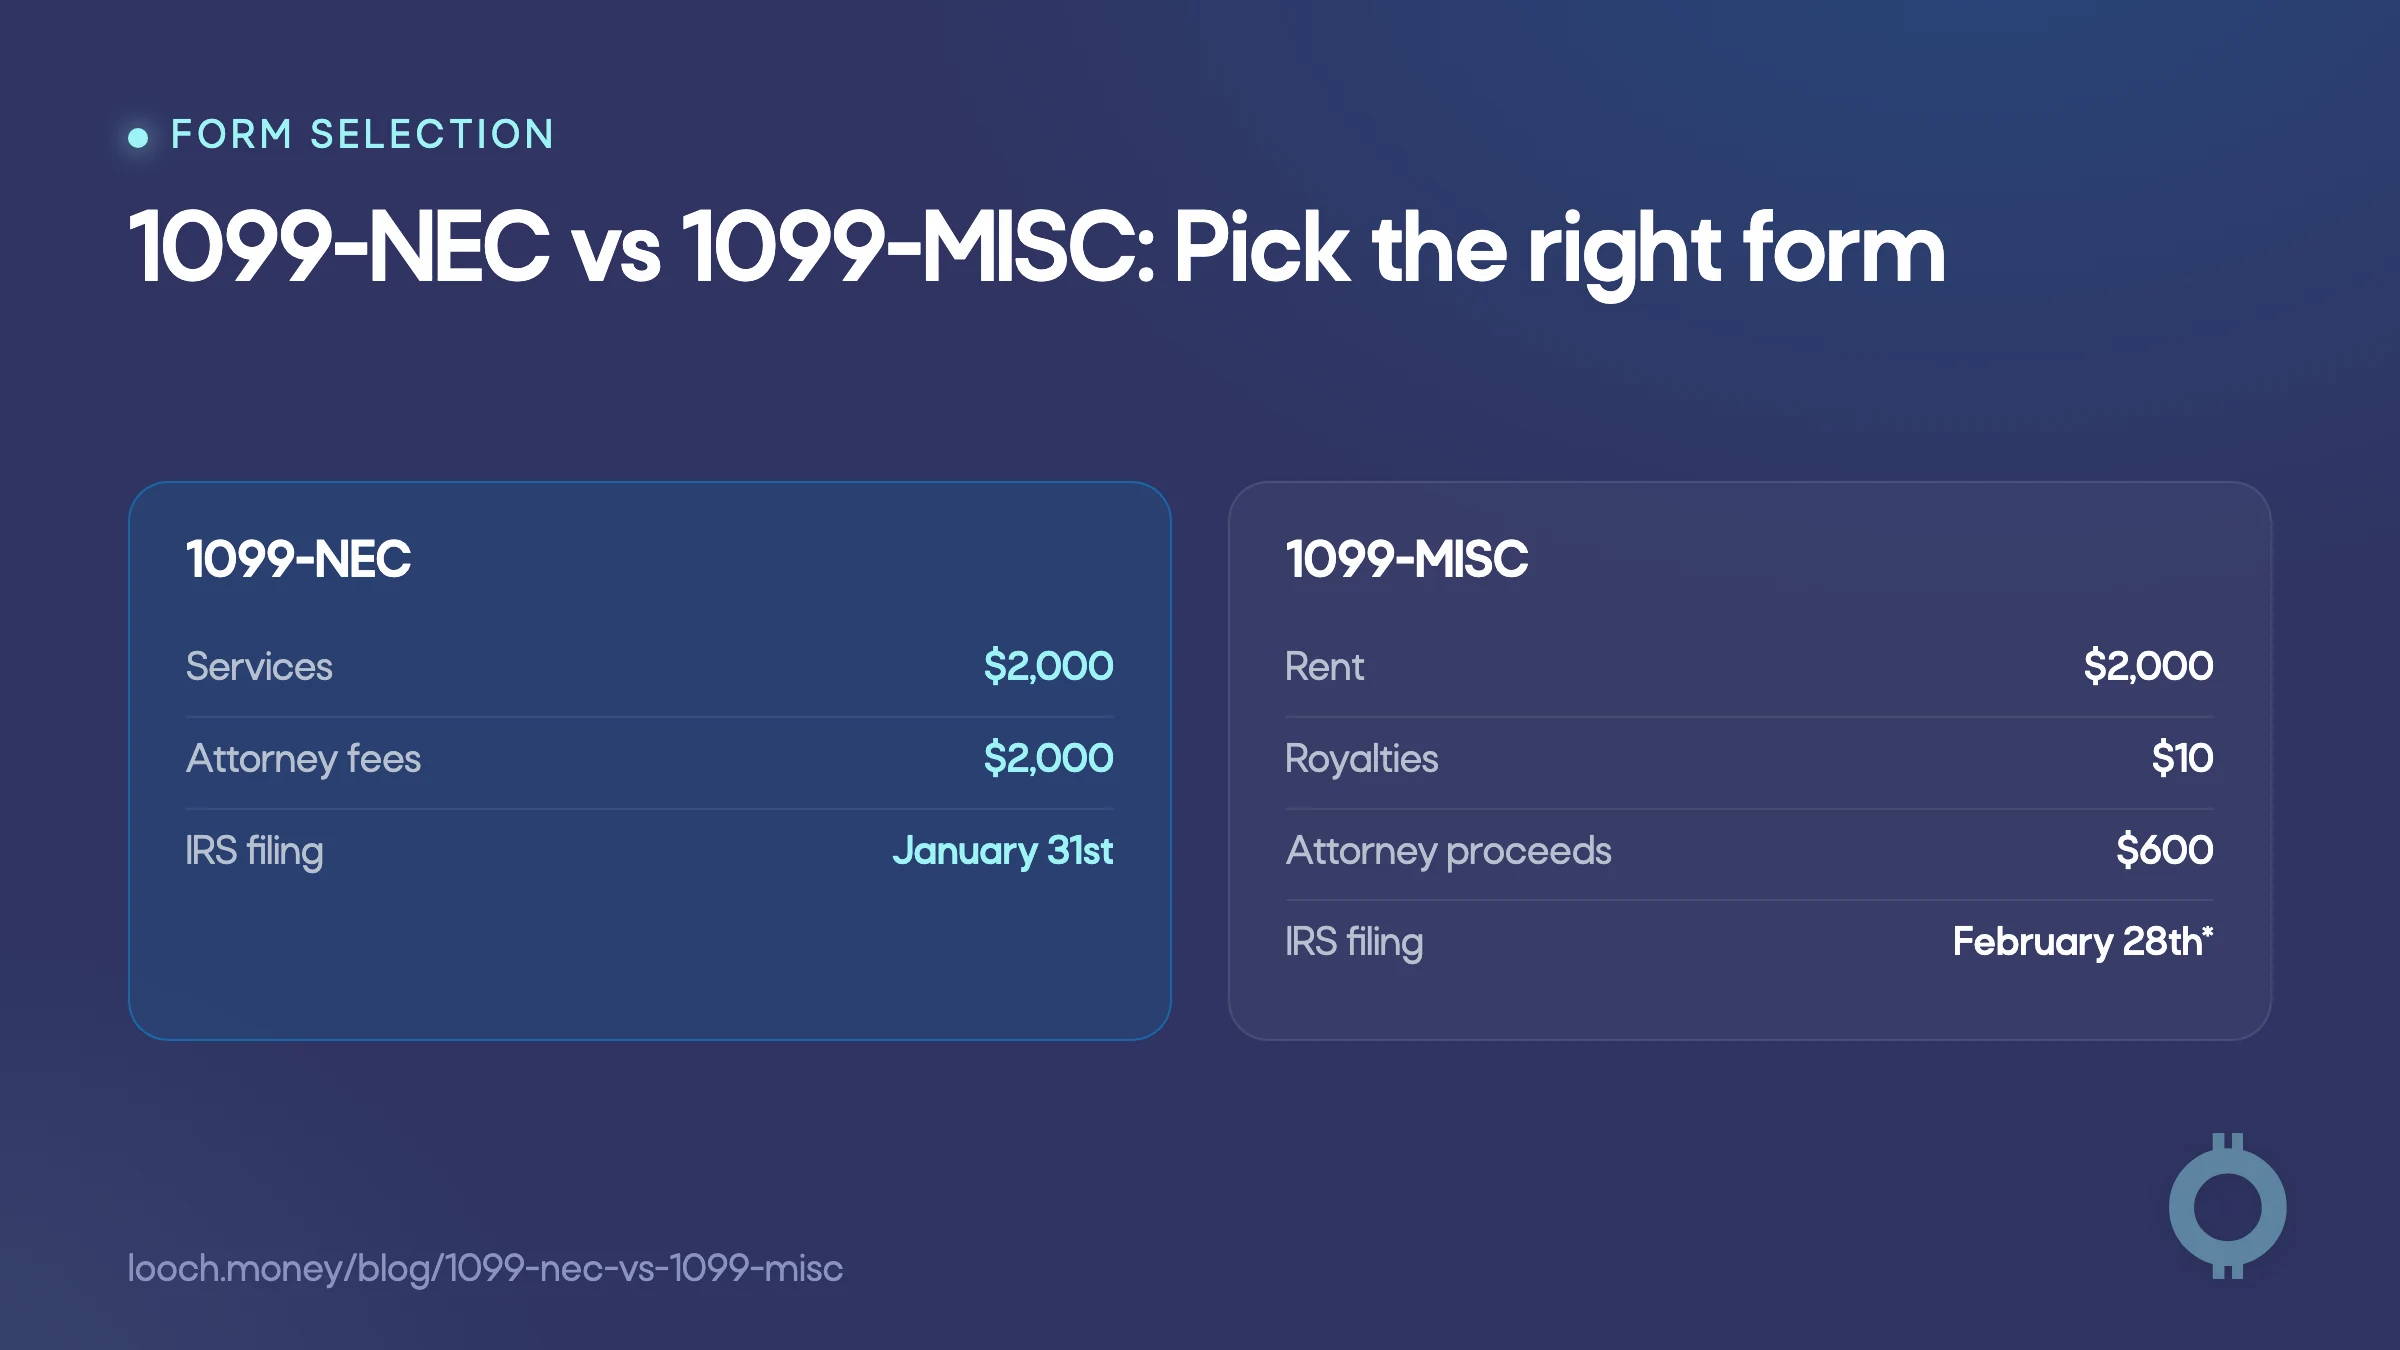
The answer is usually straightforward: Pay a non-employee for services and use Form 1099-NEC. Pay rent, royalties, certain prizes, medical payments, or attorney settlement proceeds and use Form 1099-MISC.
The threshold isn’t one universal rule. The $2,000 reporting threshold that took effect for payments made after December 31, 2025 applies to most of these boxes, but royalties and attorney gross proceeds follow different floors under the IRS instructions.
| Payment | Form and box | Threshold |
|---|---|---|
| Nonemployee compensation for services | 1099-NEC, box 1a | $2,000 |
| Attorney fees for legal services | 1099-NEC, box 1a | $2,000 |
| Gross proceeds paid to an attorney | 1099-MISC, box 10 | $600 |
| Rents | 1099-MISC, box 1 | $2,000 |
| Royalties | 1099-MISC, box 2 | $10 |
| Prizes and awards not paid for services | 1099-MISC, box 3 | $2,000 |
| Medical and health care payments | 1099-MISC, box 6 | $2,000 |
The filing calendar also depends on the form. For tax year 2026, January 31st and February 28th, 2027 both fall on a Sunday, shifting those deadlines to Monday, February 1st and Monday, March 1st, 2027.
Last verified: August 26th, 2026.
This page answers the form-selection question. For the broader process, including who must file and how to prepare the return, see our guide to filing 1099s.
The form follows what the payment was for
Form 1099-NEC is for nonemployee compensation. In plain terms, that means a payment of $2,000 or more for services performed by someone who isn’t your employee, made in the course of your trade or business. Contractor fees, freelancer invoices, commissions, and prizes or awards for services belong in box 1a when they meet the reporting threshold.
A designer, consultant, lawyer, or contractor may all receive a 1099-NEC when you paid them for their work. The deciding fact isn’t their job title. It is whether the payment was compensation for services.
Form 1099-MISC covers reportable business payments that aren’t compensation for services. It includes rent for business property, royalties, prizes that weren’t payment for work, medical and health care payments, and certain payments involving attorneys.
The split exists because nonemployee compensation moved back to its own form before the 2020 filing season. That gives the NEC an earlier IRS deadline and makes payment classification worth getting right before filing season starts.
A foreign payee can change the analysis before you select either form. A foreign person generally provides a W-8 rather than a W-9. Our guide to W-8BEN-E or W-9: Which form applies explains where that distinction starts.
Most boxes use $2,000, but royalties and attorney proceeds do not
For payments made after December 31, 2025, most relevant reporting thresholds rose from $600 to $2,000. The IRS notes that the figure may be adjusted for inflation beginning in 2027. That change is important, but treating it as a universal threshold creates two common filing mistakes.
Royalties report at $10. Box 2 of Form 1099-MISC keeps its $10 threshold. A $50 royalty payment can still be reportable even though it falls well below the general threshold.
Attorney gross proceeds report at $600. Box 10 of Form 1099-MISC keeps its $600 threshold because it is governed by a different code section than the one amended by the threshold change.
The practical move is to identify the payment type first, then check the threshold for that specific box. Don’t start with a threshold and work backward. That’s how a royalty payment or settlement payment gets sorted into the wrong filing workflow.
Attorney payments can require either form
Attorney payments are the clearest example of why the payment’s purpose matters more than the payee’s title.
- Attorney fees paid for legal services belong on the 1099-NEC in box 1a once they reach $2,000 in the year.
- Gross proceeds paid to an attorney belong on the 1099-MISC in box 10 once they reach $600, such as a settlement check paid to a claimant’s attorney in connection with legal services.
The usual corporate exemption doesn’t apply to payments to law firms. A law firm can be reportable even when it’s organized as a corporation.
The same business can also have both categories in the same year. For example, a business may pay its own counsel for legal work and separately send settlement proceeds through another attorney. Those payments have different reporting treatment because they represent different things.
If a settlement includes mixed components, or the payment records don’t clearly separate fees from proceeds, don’t force an answer from a form picker. Ask a CPA or enrolled agent to review the transaction before you file.
A few exceptions override the usual sorting rule
Some cases need attention even after you’ve identified the correct form. Direct sales of $5,000 or more require checking a box rather than entering an amount on either form, but only one form.
| Situation | What changes |
|---|---|
| Direct sales of $5,000 or more | You check a box rather than enter an amount on either form, but only one form. Using the 1099-NEC brings the January 31 filing date. |
| Backup withholding | If you withheld federal income tax, you file for that payee regardless of the payment amount, including $50 below every floor. |
| Ten or more returns | The electronic filing requirement counts information returns across form types in aggregate. At 10 or more, you must file electronically. |
These rules are easy to miss because they aren’t about the ordinary payment threshold. Keep the supporting payee information and payment records organized as you go, rather than trying to reconstruct the facts after the year closes.
The 1099-NEC has an earlier IRS deadline
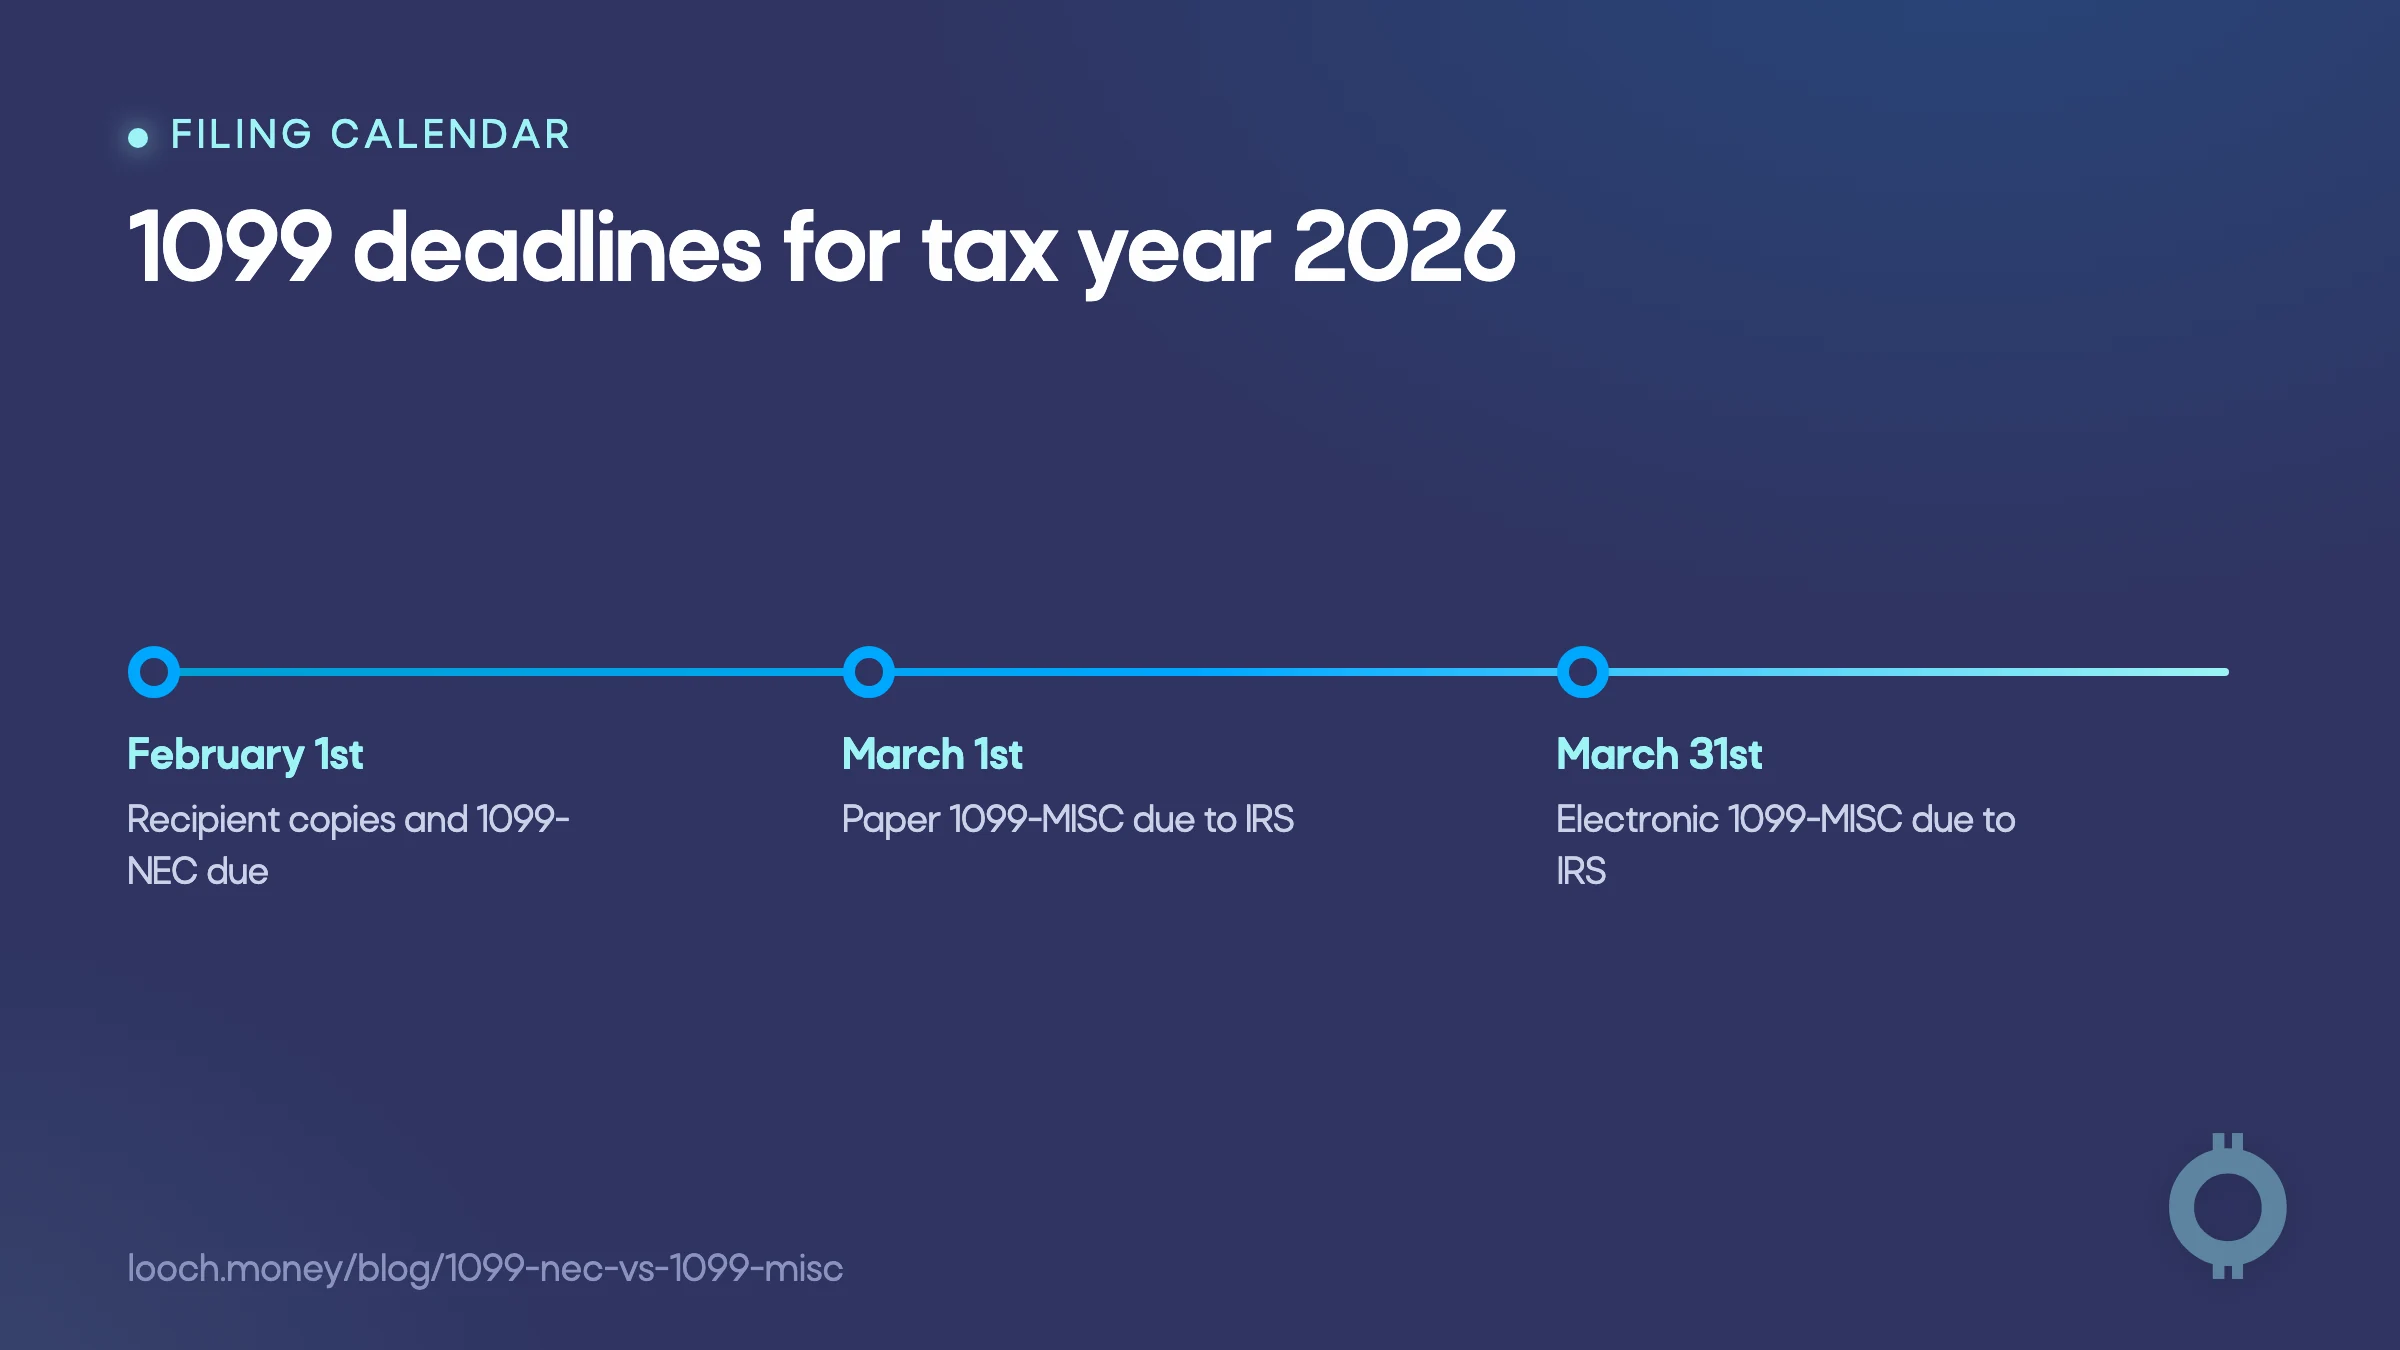
Both forms require a recipient copy by January 31. The IRS filing date is where they split.
| Form | Recipient deadline | IRS deadline |
|---|---|---|
| 1099-NEC | January 31 | January 31, on paper or electronically |
| 1099-MISC | January 31 | February 28 on paper or March 31 electronically |
When a deadline falls on a weekend, it moves to the next business day. That makes tax year 2026 1099-NEC forms due Monday, February 1st, 2027. A paper 1099-MISC is due Monday, March 1st, 2027, while the electronic deadline remains Wednesday, March 31st, 2027.
The penalty is assessed per form, not per filing batch. Missing the recipient deadline can also create a separate problem from missing the IRS deadline. See the 1099 late filing penalty for the full schedule and the difference between the two obligations.
looch turns payment records into a filing decision
The hard part is rarely finding a blank form. It’s sorting a year of transactions into reportable payments, excluded payments, correct payees, correct forms, and the correct deadlines.
looch AI makes the 1099 determination from your actual transactions, identifying which payments are reportable and which to leave out. At tax season, looch files each 1099 instantly for $2 per filing, as published on looch pricing.
That doesn’t replace professional judgment for a genuinely unclear payment. A settlement with both fees and proceeds, an uncertain payee classification, or an unusual multi-state situation deserves review from a CPA or enrolled agent. The right workflow is simple: Let your records do the routine sorting, then bring in an expert where the facts don’t fit a clean box.
Sources: Instructions for Forms 1099-MISC and 1099-NEC for box thresholds and filing dates, and the IRS Form 1099-NEC and independent contractors FAQ for the payments-after-December-31st-2025 effective date.


